
China
China’s solar capacity surpasses coal, reshaping the nation’s energy mix

By Liu Zhiqiang, People’s Daily
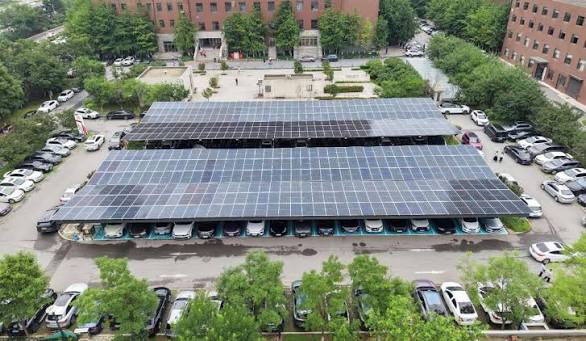
As of late July this year, China’s installed solar power capacity officially surpassed that of coal-fired generation for the first time, establishing solar as the country’s largest source of electricity-generating infrastructure.
This milestone stands in stark contrast to the industry’s struggles just over a decade ago. At that time, many small and medium-sized manufacturers were fighting for survival, while even leading firms reported substantial losses — forcing some to shutter operations entirely.
Today, however, China not only holds the world’s largest installed solar capacity year after year but has also cultivated the most comprehensive and globally competitive solar value chain.
How was such a dramatic transformation achieved in little more than ten years?
The journey began in the first decade of this century, when China’s fledgling solar sector experienced explosive growth. By the end of 2010, China’s output of solar cells had climbed to 8,000 megawatts, accounting for about half of the global total.
Yet rapid expansion masked deeper structural vulnerabilities.
First, the industry relied on overseas suppliers for raw materials and equipment, while its main markets were abroad: more than 90 percent of polysilicon was imported, more than 70 percent of products were exported to Europe and the United States, and foreign brands dominated production lines.
Second, the industry remained stuck at a relatively low level of development, relying largely on imitation, replication, and processing materials supplied by others, with excessive duplication of investment and limited technological capabilities.
These weaknesses were exposed starting in 2011, when several Western countries launched anti-dumping and countervailing investigations against Chinese solar products, dealing a major blow to the industry. Markets contracted sharply, and the industry entered a downturn.
Ultimately, overreliance on external inputs and downstream markets eroded industrial autonomy, while confinement to low-margin activities stifled competitiveness — the twin roots of the crisis.
Recognizing these challenges, Chinese policymakers responded with coordinated, forward-looking interventions. Beginning in 2012, central and local authorities rolled out a comprehensive policy framework spanning manufacturing standards, market deployment, fiscal incentives, and tax reforms.
Designed to accelerate the transition toward a modern energy system, these measures revitalized the sector and ushered in what industry observers have called a “second spring. ” On the demand side, the government deliberately expanded domestic consumption to absorb excess capacity.
In 2013, the State Council issued guidelines on promoting the sound development of the solar industry, calling for the wider application of distributed solar power and the development of solar power plants.
Starting in 2015, China launched a “top runner” program for solar power generation, accelerating the commercialization and wider application of technological advances. From 2021, large-scale renewable energy bases were developed in deserts and other arid areas, creating vast expanses of solar panels across the country’s deserts and wastelands.
These efforts supported the green transition while tapping domestic demand, leading solar power plants to spring up across the country and driving demand for solar equipment.
International markets broadened in parallel. Moving beyond traditional exports to Europe and North America, Chinese solar firms increasingly engaged in the Middle East and Southeast Asia, shifting from simple product sales to integrated solutions encompassing project financing, engineering management, brand development, and long-term operations. This evolution has steadily expanded China’s network of global partners in the clean energy sector.
Simultaneously, the supply side underwent a rigorous push for technological self-reliance. Breakthroughs emerged across multiple areas of solar module manufacturing technology. The conversion efficiency of crystalline silicon solar cells has set new world records time and again. Research and development of next-generation technologies such as perovskite solar cells has accelerated. Technologies including new-type energy storage and ultra-high-voltage power transmission gradually matured, helping address the intermittency and volatility of solar power generation.
Joint efforts by enterprises, universities, research institutes and the user end have driven continuous upgrades in China’s solar products and power generation technologies.
Backed by a complete industrial system and massive application scenarios, it fostered a virtuous cycle between supply and demand. The sector effectively reduced its heavy reliance on imported raw materials and equipment as well as overseas end markets, and its competitiveness grew steadily.
Today, China accounts for more than 90 percent of global polysilicon, wafer and solar cell production capacity and more than 80 percent of global module production capacity, while domestically made equipment has become the backbone of solar production lines. The average cost of solar power generation has fallen sharply.
Clean, cost-effective and reliable, solar power has built its competitiveness on solid technological and industrial capabilities. Its share of China’s total installed power capacity has risen from less than 0.2 percent in 2011 to 31.5 percent today.
Looking back at the development of China’s solar industry, one can see a clear path and valuable lessons for nurturing and growing emerging industries. It was the unwavering pursuit of high-quality development, the full and accurate implementation of the new development philosophy, and accelerated efforts to foster a new development paradigm that enabled China’s solar industry to turn challenges into opportunities and build up strength for sustained growth.
China is now at a critical stage of shifting from old growth drivers to new ones and upgrading its industrial structure, with businesses in some sectors facing new circumstances and challenges. The development of China’s solar industry shows that the challenges confronting an industry can also provide a valuable opportunity for adjustment and upgrading. As long as development continues to move toward higher quality and greater value, industries can weather cycles and keep moving forward under pressure.
By Ouyang Minggao
A global energy revolution is underway, centered on replacing fossil fuels with renewable energy and gasoline and diesel vehicles with electric vehicles (EVs). China is spearheading this shift, and developing a new power system integrating source, grid, load, and storage is an inevitable path forward.
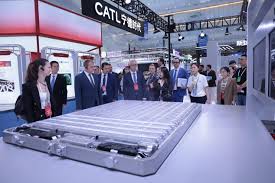
As the stock of new energy vehicles climbs toward the 100-million mark, massive numbers of EVs will transcend their traditional role as transportation tools. They are emerging as a critical component of the next-generation power infrastructure.
China is expected to have 110 million to 160 million EVs on the road by 2030, with the number projected to rise to 300 million to 400 million by 2040. As ultra-fast charging networks expand, the strain of synchronized charging on local grids is becoming increasingly apparent.
For instance, if 5 million EVs were to charge simultaneously overnight at 10 kW each, the resulting demand — 50 million kW — would far exceed the peak capacity of most municipal grids.
Shifting EV charging from unmanaged, decentralized charging to coordinated, bidirectional energy flow, is therefore crucial. The key lies in enabling vehicle-to-grid (V2G) technology, which allows EVs to interact dynamically with the power network.
At its core, V2G transforms EVs from passive grid consumers into active, mobile energy storage units. Vehicles can draw power during off-peak hours and feed electricity back into the grid during periods of high demand.
This not only alleviates grid congestion but also creates new revenue streams for owners who participate in wholesale energy markets.
With an average 70-kWh battery pack, leveraging surplus cycling capacity for grid services could generate cumulative lifetime returns of 15,000 to 75,000 yuan ($2,240 to $11,198). In effect, EVs are shifting from depreciating consumer products to income-generating assets.
Battery life and safety are among the public’s major concerns. Research shows that properly managed V2G operations do not accelerate battery degradation; on the contrary, they can help extend battery calendar life.
Current lithium iron phosphate (LFP) batteries used in EVs can undergo about 3,000 full charge-discharge cycles before their capacity falls to 70 percent. Yet a typical household vehicle consumes only about 500 cycles over 10 to 15 years of use, leaving substantial capacity for additional applications.
Technologies such as bidirectional pulsing can achieve more uniform lithium distribution, suppress lithium plating, and boost fast-charging and low-temperature performance. Meanwhile, V2G operation keeps batteries mostly at a partial state of charge. This prevents calendar-life degradation caused by long-term storage at full charge. When paired with intelligent risk monitoring, these systems effectively minimize safety incidents.
V2G applications have already taken shape in three typical scenarios.
The first is the “point” scenario in industrial parks, where vehicle batteries operate in coordination with photovoltaic generation and energy storage facilities.
The second is the “line” scenario in transportation, where integrated solar-storage-charging systems and batteries used for swapping at heavy-truck stations can supply power to passenger vehicles, reducing the impact on the main power grid.
The third is the “area” scenario in buildings, where integrated “home-vehicle-grid” systems enable comprehensive management of building energy use and V2G operations.
Looking ahead, V2G is expected to become a major form of distributed short-duration energy storage in China. Given that high-rise buildings dominate China’s urban landscape and that conditions for installing fixed energy storage systems at home are limited, using EVs parked in underground garages for energy storage is a more practical option.
Under China’s 15th Five-Year Plan (2026-2030) for the development of the new type of power system, the aggregate adjustable charging capacity enabled by V2G is expected to reach 50 million kilowatts by 2030. By 2040, as the growth of fixed energy storage slows, V2G energy storage capacity could exceed 4 billion kilowatt-hours.
Conservatively estimated, the total battery capacity of 350 million EVs will reach 25 billion kilowatt-hours by 2050, enough to meet the country’s electricity demand for one day in an emergency.
The next five years will be a launch phase for the V2G industry. As technical standards are improved, market mechanisms are put in place and business models mature, more than 100 million EVs will effectively form a vast network of “mobile power banks” for the grid, providing strong support for energy transition.
(Ouyang Minggao is an academician of the Chinese Academy of Sciences and a professor at Tsinghua University. The article was compiled by People’s Daily journalist Wang Zheng.)
By Cheng Sen
Chinese brands are increasingly capturing global attention in the consumer electronics sector.
Early this September, they took center stage at IFA Berlin, the world’s leading consumer electronics trade show. On display were Chinese humanoid robots advancing into real-world application scenarios and smart home products featuring proactive sensing and collaborative AI services.
Not long ago, the smartphone industry saw a “super release week” for foldable phones. Huawei, Xiaomi, and Apple unveiled their respective flagship products within 72 hours, putting leading Chinese and international brands against each other in the same product category and sparking widespread discussion.
Such moments are no longer outliers; they reflect a broader industrial shift.
Decades ago, China’s manufacturing base was comparatively underdeveloped. Across many sectors, the country started late, trailing global leaders in advanced technologies, standard-setting influence, and even foundational design concepts.
Its early path forward relied heavily on imitation and incremental improvement. Today, that narrative has reversed. From artificial intelligence and new energy vehicles to robotics and aerospace reusability, China now competes on equal footing — or leads — in numerous domains. In previously uncharted territories, it has emerged as both a pioneer and a rule-maker.
These breakthroughs stem from the cumulative power of scientific and technological innovation. Take the smartphone industry as an example. Ultimately, it is exclusive cutting-edge technologies that have empowered Chinese brands to march into the high-end market. Breaking free from the lower rungs of industrial and value chains represents an arduous uphill growth, as well as the continuous forging of brand competitiveness and technological “moats.”
None of this would have been possible without a highly coordinated innovation ecosystem.
The numbers tell a clear story. The World Intellectual Property Organization recently released its report on the world’s top 100 innovation clusters as part of the Global Innovation Index 2026. China is home to 25 of the world’s top 100 innovation clusters, the largest number for the fourth consecutive year. The Shenzhen-Hong Kong-Guangzhou cluster ranked first for the second consecutive year. As a cornerstone of China’s national innovation ecosystem, these regional innovation clusters reflect the steady growth of China’s capacity for scientific and technological innovation.
Progress is driven by clear strategic priorities: state support for sci-tech advancement, the cultivation of advanced, locally adapted industrial capabilities, and targeted policy incentives.
Equally important is the sheer scale and dynamism of the country’s domestic market, which generates rich application scenarios for iterative testing and commercialization.
Underpinning both is a deepening talent pool, fueled by tighter integration across education, research, and industry — a virtuous cycle that continually upgrades the quality and distribution of skilled professionals.
All these ground-laying efforts nurture sparks of innovation and creativity, unleashing momentum for high-quality development.
Yet a clearer understanding of how China’s innovation-driven model works also makes it harder to sustain certain misconceptions.
For years, some policymakers and media outlets have amplified warnings about a so-called “China Shock 2.0,” attributing China’s progress in high-end manufacturing to industrial subsidies and stoking anxiety in the process.
In practice, as one international observer noted, China operates like “the world’s toughest gym.” Competition and innovation are embedded in its development model. Rather than delivering a disruptive “shock,” China’s progress expands global opportunities; rather than displacing foreign competitors, it often creates new markets and capabilities.
The evidence is mounting. Volkswagen has adjusted its R&D plans at its headquarters in Wolfsburg based on the model of its R&D center in Hefei, east China’s Anhui province. Chinese AI models have ranked first for 20 consecutive weeks in terms of weekly global usage among large AI models.
As a new round of scientific and technological revolution and industrial transformation converges with China’s historic transition in its development model, China is pressing ahead with innovation and working to build itself into a global source of scientific and technological innovation. With such fertile ground for development, China is set to continue surprising the world with innovation.
By Yu Xuan, People’s Daily
In today’s global economy, robust domestic markets are among the most scarce and sought-after resources. Investors increasingly regard China’s market as a rare asset — even among rare assets.
What sets it apart? A single word offers a useful starting point: stability.
This stability is most visible in the quiet continuity of everyday life. Two comparisons help clarify why.
First, the contrast with other major economies. As inflation has risen significantly in major developed economies, with prices still surging and the cost of basic necessities putting growing pressure on household budgets, Chinese consumers have continued to enjoy relatively affordable essentials. Official data supports this observation: China’s consumer price index rose 0.8 percent year on year in August, a modest increase that underscores the steady rhythm of daily life for ordinary citizens.
Second, the shift from past vulnerabilities to present resilience. There was a time when summer power outages and factory shutdowns were a major concern. Today, power rationing has become a rare sight. In August, China’s total electricity consumption once again exceeded 1 trillion kilowatt-hours, with power demand reaching a record high. Yet cities continued to function smoothly, and homes remained brightly lit as usual.
This reliability stems from a modernized, multi-layered energy infrastructure. From ultra-high-voltage transmission corridors and rural distribution networks to integrated urban microgrids, China’s power system seamlessly blends conventional thermal generation with wind, hydro, and solar sources. The result is a resilient grid that keeps economic and social activities running smoothly.
In a world marked by sluggish recoveries, geopolitical tensions, and volatile energy prices, such stability carries immense value. It provides a rare anchor of predictability.
Notably, the International Monetary Fund recently revised its global growth forecast downward by 0.1 percentage points for the year, while raising its projection for China’s growth by 0.2 percentage points. This divergence reflects growing confidence in China’s economic resilience — and helps explain why international investors are steadily increasing their capital commitments.
Where does this stability come from? The institutional strengths of China’s system serve as its anchor.
Consider the example of Dadukou district in southwest China’s Chongqing municipality. Once known for its vast steel industry, the district faced a key question after the relocation of Chongqing Iron & Steel Co., Ltd.: how could it build new industries to replace the old? Drawing on its existing strengths, the district made a strategic decision to develop the motorcycle industry.
The market and the government have worked in tandem. Under expedited regulatory approvals, Qianjiang Motorcycle Group moved into its new smart manufacturing facility as soon as construction was completed. Today, components supplied by Qiutian Gear are used in one out of every five motorcycles manufactured globally, while Lide Industry commands nearly half of China’s domestic clutch market.
Sound industrial planning, targeted policy support and continuously improving services have helped establish a well-integrated industrial ecosystem within a 15-minute radius in the city.
Balancing dynamism with order is essential. With more than 350 companies competing in the same industry, how can the market remain vibrant without descending into disorder? The key lies in close coordination across the industrial chain and differentiated competition.
Companies carve out specialized market niches while extending and strengthening the industrial chain, fostering closer integration between manufacturing and consumption, and between industry and tourism.
From January to August this year, the industrial output of enterprises above the designated size in Dadukou district’s high-end motorcycle sector grew 27 percent year on year. Motorcycle manufacturing, riding, and motorsports events have all become part of the district’s identity, demonstrating how to give the market room to thrive while ensuring effective regulation.
“Combining an efficient market with a well-functioning government” is not only a distinctive strength of China’s socialist market economy, but also a key principle for economic and social development during the 15th Five-Year Plan period (2026-2030). By continuing to improve macroeconomic governance, upgrade traditional industries, expand emerging industries, and plan ahead for future industries, China will further strengthen the certainty and distinctive appeal of its market.
The stability of China’s economy is not static. It is a high-level dynamic equilibrium maintained as the economy continues to advance. Behind it lie strategic resolve and a proactive approach to shaping the country’s future.
“It’s not venture capital, but industrial investment; not gambling, but striving,” said an official in Hefei, east China’s Anhui province, who remains clear-headed despite the praise the city has received for its investment success.
High returns on industrial investment are only the visible results. The underlying strengths lie in a more fundamental approach: adapting to local conditions, making decisions based on sound analysis, and taking a long-term view.
Instead of chasing every fleeting trend in a frenzy, China stays focused on innovation within chosen sectors. Instead of faltering amid headwinds, it stays anchored to the goal of fostering new quality productive forces. Instead of fixating merely on tangible, immediate gains, it devotes more to laying the groundwork for long-term returns.
This poised mindset, balancing strategic steadiness with tactical agility, embodies the Communist Party of China’s view on political achievements and development. It grows from a forward-evolving governance system, manifests in the tireless endeavors of hundreds of millions of market entities, and quietly shapes people’s steady expectations of Chinese modernization. Such confidence in the path forms the bedrock for China’s sustained and sound economic growth.


China leverages electric vehicles to stabilize the power grid

KW-IRS Staff Threaten Strike Over Alleged Poor Remuneration

A continuously innovating China is a land of opportunity

-
 Uncategorized6 years ago
FG, states urged to harness flooding for ranching, others with technology – Agbaje
-
 Headlines11 years ago
Breaking: EFCC seals Borno House of Assembly, as Hon members take to their heels
-
 News12 years ago
Nigeria Security Operatives Stage Manhunt For Homosexual Perpetrator
-
 News10 years ago
How 21-year-old Girl fled community over accusation of lesbianism
-
 News11 years ago
Yobe Gov Moves Against Deputy
-
 Opinion7 years ago
7 signs she has friend zoned you
-
Technology5 years ago
Online job placement company headhunts women
-
 Headlines10 years ago
Borno Dep Gov Abducts Another Church Leader