
News
BUDGET OFFICE OF THE FEDERATIONRESPONSE TO THE 2026 U.S. DEPARTMENT OF STATE FISCAL TRANSPARENCY REPORT ON NIGERIA

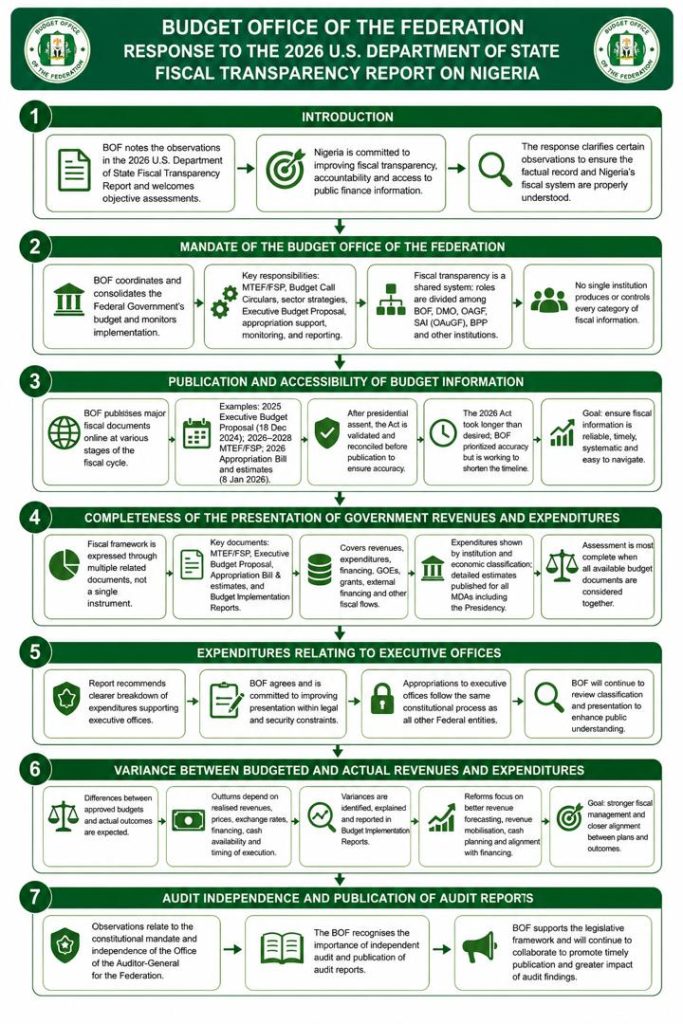
- Introduction
The Budget Office of the Federation (BOF) notes the observations on Nigeria contained in the 2026 Fiscal Transparency Report of the United States Department of State. The Federal Government welcomes objective assessments of its public financial management system and remains committed to the continuous improvement of fiscal transparency, accountability and access to public finance information.
The Report acknowledges important areas in which Nigeria meets fiscal transparency requirements, including the public availability of the enacted budget and end-of-year fiscal information; the disclosure of debt obligations, including major state-owned enterprise debt; the legal and disclosure framework governing the sovereign wealth fund; and the existence and application of statutory procedures governing natural-resource extraction contracts and licences.
Other observations in the Report require clarification when considered in the context of Nigeria’s institutional allocation of responsibilities and the range of budgetary and fiscal information already in the public domain. The purpose of this response is therefore not to dispute the value of external scrutiny, but to ensure that the factual record and the structure of Nigeria’s fiscal system are properly understood. - Mandate of the Budget Office of the Federation
The BOF is responsible for coordinating the preparation and consolidation of the Federal Government’s budget, and for monitoring and reporting on its implementation within the framework established by law and government fiscal policy.
Its responsibilities include coordinating the preparation of the Medium-Term Expenditure Framework and Fiscal Strategy Paper (MTEF/FSP); issuing Budget Call Circulars; coordinating the preparation of Medium-Term Sector Strategies; coordinating the preparation and consolidation of the Executive Budget Proposal; supporting the appropriation process; monitoring budget implementation; and producing periodic Budget Implementation Reports.
These responsibilities form part of a wider public financial management system in which different institutions perform duties assigned to them by the Constitution and by statute. Debt recording and management fall principally within the remit of the Debt Management Office; government accounting, treasury and cash-management functions reside principally in the Office of the Accountant-General of the Federation; external audit is constitutionally assigned to the Office of the Auditor-General for the Federation; while federal procurement operates within the statutory framework administered by the Bureau of Public Procurement and individual procuring entities.
The observations in the Report are therefore best considered in the context of this institutional division of responsibility. Fiscal transparency is the product of an interconnected system; no single institution produces or controls every category of information on which an assessment of the entire system must depend. - Publication and Accessibility of Budget Information
The Report recommends that Nigeria make its Executive Budget Proposal widely and easily accessible to the public, including online. The BOF respectfully notes that the online publication of the Executive Budget Proposal and other major budget documents has, for several years, formed part of the Federal Government’s established budget process.
The BOF routinely publishes major documents produced at successive stages of the fiscal cycle. These include the MTEF/FSP, the Executive Budget Proposal and detailed estimates, Appropriation Acts, implementation guidelines, and periodic Budget Implementation Reports.
For example, the 2025 Executive Budget Proposal was published on the BOF website on 18 December 2024 alongside the 2025 Appropriation Bill. The 2026-2028 MTEF/FSP was similarly published, while the 2026 Appropriation Bill and its detailed estimates were placed on the BOF website on 8 January 2026.
The purpose of continuing reform, therefore, is not to create a practice of publication where none exists, but to make an established practice more timely, systematic and easier for users to navigate. Fiscal information is useful not merely because it exists, but because it is published at the appropriate time, clearly identified and readily connected to the other documents needed to understand the fiscal picture.
Following presidential assent to an Appropriation Act, the signed instrument is subjected to validation and line-by-line reconciliation against the version passed by the National Assembly before the final budget details are reflected on the Government’s financial management platform and released for public use. This process is intended to ensure that the figures, codes and statutory references placed before the public correspond with the instrument that has become law.
For the 2026 Appropriation Act, this process took longer than would ordinarily be desirable. The Budget Office considered it preferable to complete the necessary validation before publication rather than place in the public domain figures that might later require correction. That choice protected the integrity of the published record, but the delay also demonstrates the need to shorten the interval between presidential assent and public availability.
The lesson is therefore twofold: published fiscal information must be reliable, but that reliability must increasingly be achieved without sacrificing timeliness. The BOF is reviewing its internal sequencing, validation and publication arrangements with that objective in mind. - Completeness of the Presentation of Government Revenues and Expenditures
The Report recommends that the budget provide a substantially complete picture of government revenues and expenditures. Nigeria’s fiscal framework is expressed through several related documents rather than through a single instrument. The MTEF/FSP establishes the macroeconomic and fiscal assumptions underlying the annual budget. The Executive Budget Proposal, Appropriation Bill and detailed estimates set out proposed expenditure allocations, revenue assumptions and the financing framework. Budget Implementation Reports subsequently show performance against approved benchmarks.
Taken together, these documents contain extensive information on projected revenues, expenditure proposals, financing and the operations of Government-Owned Enterprises. The budget documentation also provides information on grants, external financing and other material fiscal flows within the Federal Government’s reporting framework.
Expenditure is presented through institutional and economic classifications, including allocations to ministries, departments and agencies. The Government also publishes detailed estimates relating to the Presidency and other institutions of government, subject always to the legitimate requirements of law, national security and operational confidentiality.
The BOF therefore considers that an assessment of Nigeria’s fiscal transparency is most complete when it examines the available budget documents as a body, rather than treating any one document as though it were intended to contain the entire fiscal account.
This does not remove the need for improvement. Citizens, investors and other users of fiscal information should be able to understand the broad relationship among revenue, expenditure, financing and fiscal risks without having to reconstruct the fiscal picture from numerous documents. The Office will therefore continue to improve consolidation, cross-referencing and presentation so that information already disclosed across different fiscal documents can be more readily understood as a coherent whole. - Expenditures Relating to Executive Offices
The Report recommends a clearer breakdown of expenditures supporting executive offices. The BOF agrees with the transparency objective underlying this recommendation.
Appropriations to offices and institutions within the Executive are subject to the same constitutional appropriation process that applies to other Federal Government entities. Detailed estimates are already published within the budget documentation. Where expenditures are currently aggregated within broader administrative, personnel or service-wide classifications, there remains scope to improve their presentation without compromising legitimate security, statutory or operational considerations.
The BOF will accordingly continue to examine the classification and presentation of such expenditures with a view to improving public understanding within the applicable legal and security framework. - Variance Between Budgeted and Actual Revenues and Expenditures
The Report observes that actual revenues and expenditures did not reasonably correspond with the enacted budget. The BOF considers that this observation would benefit from greater precision regarding the standard against which such correspondence is being assessed.
An appropriation is an authority to spend; it is not, in every circumstance, a guarantee that the entire amount appropriated will become available in cash. Actual fiscal outcomes depend on realised revenues, oil production and prices, tax collections, exchange rates, financing conditions, cash availability and the timing of expenditure execution. A difference between an approved budget and the eventual outturn must therefore be interpreted rather than merely observed.
The central transparency question is whether material deviations are identified, explained and reported. This is one of the purposes of the Budget Implementation Reports produced by the BOF, which compare revenue and expenditure performance against approved benchmarks and explain significant departures from the fiscal plan.
At the same time, persistent or unusually large differences between appropriations and outturns can weaken the usefulness of the budget as an instrument of economic management. The Government’s continuing reforms therefore place greater emphasis on realistic revenue forecasting, improved revenue mobilisation, stronger commitment controls, better cash planning and closer alignment between appropriations and available financing. - Audit Independence and Publication of Audit Reports
The observations concerning the independence of the Supreme Audit Institution and the publication of audit reports relate principally to the constitutional and statutory mandate of the Office of the Auditor-General for the Federation and to the wider legislative framework governing public audit.
The BOF supports a strong and independent external audit function as an essential component of fiscal accountability. It will continue to provide the budgetary and implementation information required within its mandate and to cooperate with the Office of the Auditor-General for the Federation and other oversight institutions.
Institutional or legislative questions concerning the independence, powers and publication obligations of the Supreme Audit Institution are, however, appropriately addressed in conjunction with the Office of the Auditor-General for the Federation, the National Assembly and other authorities responsible for the applicable legal framework. - Public Procurement Information
Federal procurement is governed by the Public Procurement Act and the institutional framework administered by the Bureau of Public Procurement, while procurement transactions are undertaken by individual procuring entities. The recommendation concerning the publication of accessible information on procurement contracts should therefore be addressed principally through that framework.
The BOF nevertheless recognises the close relationship among appropriation, procurement, commitment and payment. Greater interoperability among budget, procurement and treasury information systems would materially improve the public’s ability to follow expenditure from appropriation through procurement to eventual payment and delivery. The Office supports the continued development of such integrated public financial management arrangements. - Timeliness, Institutional Capacity and the Fiscal Responsibility Framework
Fiscal transparency should be treated as a continuing institutional obligation, not as an exercise undertaken solely in response to an external assessment. The experience of producing statutory fiscal reports has, however, brought into sharper focus a question that warrants attention beyond administrative improvement alone.
Fiscal reports are assembled from numerous sources across government. Their reliability depends on the timely submission of information, reconciliation among institutions, resolution of discrepancies and verification before publication. Where these processes repeatedly require more time than the statutory reporting period permits, the response should not simply be to normalise lateness.
Government must first improve the processes that can be improved: clearer responsibility for source data, earlier submission, greater automation, greater interoperability among systems and stricter reporting discipline.
However, where experience over time demonstrates that a statutory deadline no longer reasonably accommodates the number of institutions, datasets and verification steps required to produce a reliable report, there is also a legitimate case for reviewing the law itself.
The purpose of the Fiscal Responsibility Act is to strengthen fiscal discipline, accountability and transparency. Its reporting provisions should therefore impose deadlines that are demanding enough to compel administrative discipline, but sufficiently realistic to permit the publication of information whose accuracy can be defended.
The Federal Government should accordingly consider, through the appropriate legislative process, whether aspects of the reporting timetable under the Fiscal Responsibility Act require amendment in the light of experience since its enactment. Such a review should not weaken reporting obligations. Its purpose should be the opposite: to establish timelines that are credible, enforceable and capable of producing reports that are both timely and reliable. - Institutional Engagement and Continuing Improvement
The Fiscal Transparency Report can also serve as a basis for constructive technical engagement. The BOF considers it useful to deepen dialogue with the United States Government and other development partners on the methodology used in fiscal transparency assessments, particularly the treatment of multiple publicly available fiscal documents, the measurement of budget credibility, and the standards applied to timeliness and accessibility.
Such engagement should be approached as an opportunity for clarification and institutional learning rather than as a dispute over the assessment. The Office may also explore appropriate technical assistance arrangements to strengthen its capacity in fiscal reporting, information management, digital publication, interoperability and public accessibility. Any such cooperation should complement Nigeria’s own reforms and operate within the Government’s legal, institutional and information-security framework. - Conclusion
Nigeria accepts the principle at the heart of fiscal transparency: citizens and other stakeholders should be able, without unnecessary difficulty, to know what the Government intends to raise and spend, what the legislature has authorised, what was eventually received and spent, and how public resources were accounted for and audited.
Nigeria has already built a substantial architecture for making this information public. The question before us is therefore not whether disclosure exists, but how to make the existing system faster, clearer, more complete and easier to understand.
There are areas in which Government must improve its own processes. There are areas in which fiscal information already exists but must be assembled and presented more coherently. There are responsibilities that belong to institutions other than the Budget Office. There may also now be statutory reporting timelines whose continued practicality deserves examination in the light of experience.
A mature system should be able to acknowledge all four points without defensiveness.
The Budget Office therefore welcomes external assessments that assist Nigeria in strengthening its institutions. It also considers it important that such assessments take account of the full range of fiscal documents made publicly available and of the constitutional and statutory division of responsibilities among institutions.
The Federal Government remains committed to a budget system in which fiscal decisions are not only lawful and disciplined, but are also increasingly transparent, accessible, intelligible and capable of independent public scrutiny.
Tanimu Yakubu
Director-General
Budget Office of the Federation
Abuja
18 August 2026
By Emmanuel Kuza
A chieftain of the Peoples Democratic Party (PDP) in Nasarawa State, Abuga Ovie, has described the name Ombugadu as a political brand, saying the popularity and wide acceptance of the name have made David Emmanuel Ombugadu a major force in the state’s political landscape.
Ovie, who stated this in an interview on Tuesday, said what started as opposition from some of Ombugadu’s biological brothers and people he described as fathers and uncles who betrayed him for personal political interests had now assumed a wider dimension, with political parties allegedly joining the battle against him.
According to him, the latest development was an attempt to undermine the political value of the Ombugadu name by presenting another person with the same surname, describing it as an indication of how far some political actors were prepared to go to weaken the PDP governorship candidate.
“Ombugadu is a brand, not a title. The people are not fools. They know their own. You cannot simply bring another person bearing the same name and expect the people to forget the political identity that Ombugadu has built over the years,” he said.
He further alleged that a former governor was working to introduce a political associate who had served as Accountant-General of Nasarawa State into the political equation, with the alleged objective of destabilising the PDP and weakening its chances by ensuring that the party fields a less competitive candidate in 2027.
“The plan, as we understand it, is to destabilise the PDP and make sure the party presents a weak candidate, thereby creating an advantage for the former governor’s preferred candidate. But all those efforts have proved abortive because the national leadership of the PDP stood its ground and refused to lose its best bet for the 2027 governorship election,” Ovie said.
The PDP chieftain said the resolve of the national leadership to retain Ombugadu had demonstrated the confidence the party had in his capacity to win the governorship election, despite what he described as attempts by some political actors to frustrate his ambition.
Ovie urged political parties and their leaders to resolve their internal differences instead of concentrating their efforts on Ombugadu, whom he compared to David in the Bible, saying he remained focused despite betrayal and opposition from those close to him.
“Ombugadu is like David in the Bible. Even when his brothers forsook him, he remained focused. Today, despite the people who have betrayed him, he remains focused and has a blueprint that can rescue Nasarawa State,” he said.
He said political parties should concentrate on presenting their programmes and convincing voters about how they intend to address the challenges confronting the state rather than expending their energy on attempts to stop Ombugadu.
“Political parties should fix their problems instead of wasting their strength fighting Ombugadu. Let everybody bring their blueprint before the people and explain what they intend to do for Nasarawa State,” he said.
Ovie maintained that the 2027 election should be about ideas, competence and the future of Nasarawa State, rather than attempts to manipulate political structures or undermine individuals perceived to enjoy strong grassroots support.
He urged the people of the state, particularly the Eggon community, to remain politically vigilant and resist what he described as efforts to make them settle for less, insisting that voters would ultimately determine who enjoys their confidence at the polls.
Reduce repeated references to Ombugadu

By Israel Adamu, Jos
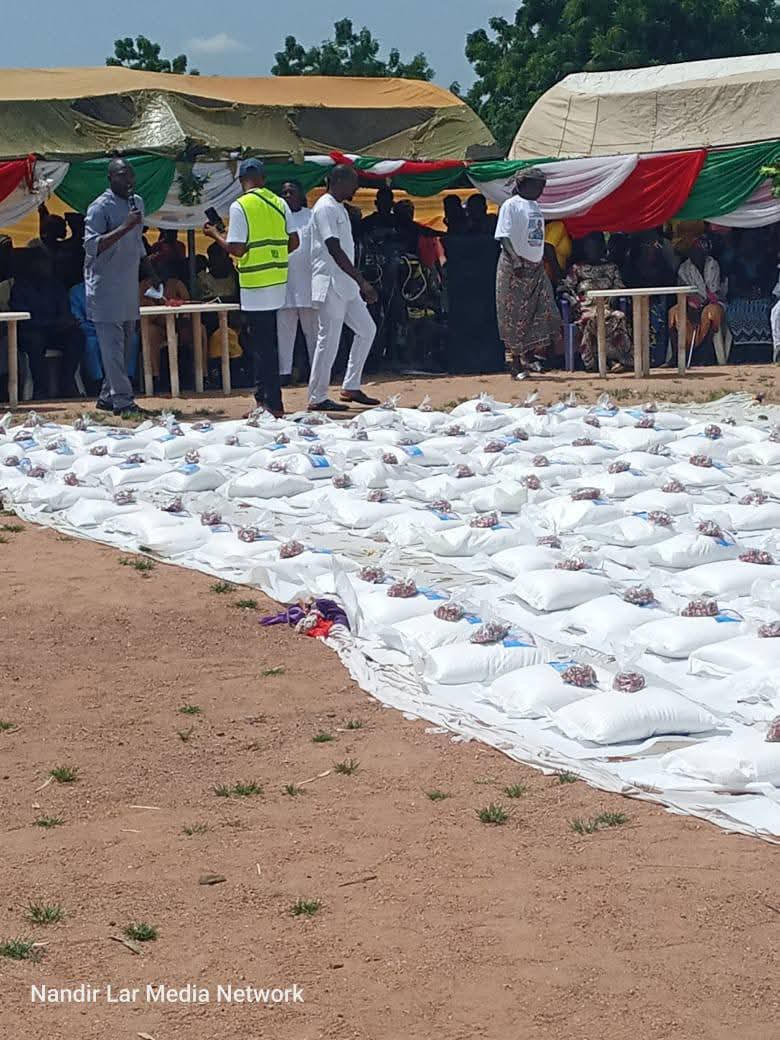
Two hundred widows from communities across Langtang North Central State Constituency of Plateau State have benefited from an empowerment outreach organised by Gimbiya Gani Nandir Lar under the Jagoran Talakawa movement.
The outreach, held at Pilgani in Langtang North Local Government Area, was aimed at supporting vulnerable women and drawing attention to the challenges faced by widows, particularly those struggling to provide food, pay school fees and meet other basic needs for their families.
The organiser, Nandir Lar, who is the All Progressives Congress, APC, candidate for Langtang North Central State Constituency, said the gesture was motivated by compassion and concern for vulnerable members of the society.
She stressed that the outreach was not a political programme but an expression of love and support for humanity.
Nandir Lar said: “The plight of widows may not always make headlines, but their struggles are real, painful and deserving of our collective attention.
“This is simply an expression of compassion and love for humanity. It is not a political programme.
“Our constituency is home to people with diverse needs, including mothers, widows and young people who are seeking opportunities to improve their lives.”
Former Provost of the Federal College of Education, Pankshin, Amos Chirfat, commended the initiative, saying it had brought smiles to the faces of vulnerable women in the constituency.
Minority Leader of the Langtang North Legislative Council, Dirya Sheni, also commended Nandir Lar for supporting widows and other vulnerable members of the community.
At the end of the outreach, each of the 200 beneficiaries received a 10-kilogramme bag of corn flour, seasoning and N10,000 cash
By Francis Wilfred
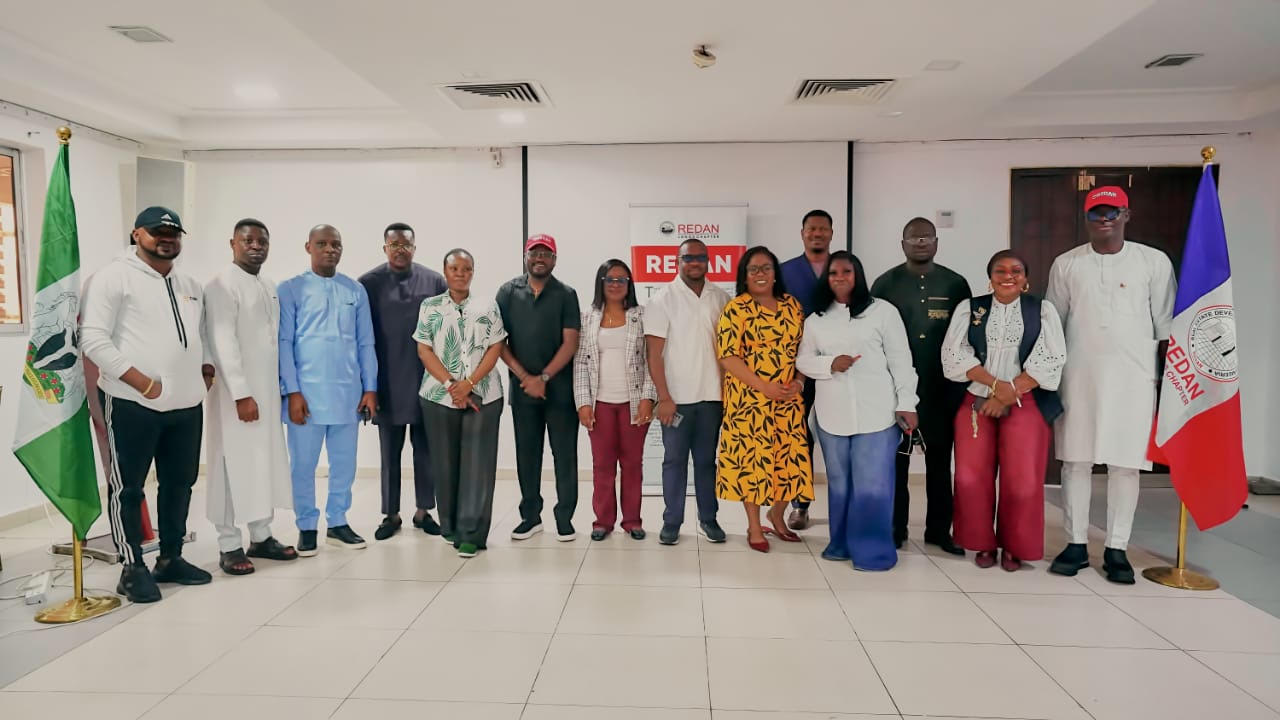
The Special Control Unit against Money Laundering (SCUML), and the Real Estate Developers Association of Nigeria (REDAN) have expressed commitment to ensure a full compliance with the Anti Money Laundering/Counter Finance on Terrorism/Counter Proliferation Financing, (AML/CFT/CPF) laws within the Nigeria’s real estate sector.
They made the resolve during a stakeholders’ engagement held on Thursday, September 10, 2026
The engagement focused on Mutual Evaluation readiness, risk-based supervision, beneficial ownership transparency, customer due diligence, internal controls and stronger collaboration between SCUML and the real estate sector.
Assistant Commander of the EFCC, ACE 1 Ibinabo Amachree, speaking on behalf of SCUML highlighted the strategic role of real estate operators in protecting the integrity of Nigeria’s financial system, particularly given the sector’s vulnerability to money laundering and other financial crime risks.
Amachree encouraged REDAN members to move beyond registration to ensure that compliance is embedded in their day-to-day operations. He mentioned the areas to include: understanding institutional risks, knowing customers and beneficial owners, identifying politically exposed persons, conducting appropriate sanctions screening, maintaining effective internal controls and meeting applicable reporting obligations
He, therefore, reaffirmed readiness to working closely with REDAN and other stakeholders to improve compliance, build capacity and promote a stronger culture of accountability across the real estate sector
“The message is clear: effective compliance is not just about meeting regulatory requirements; it is about protecting businesses, strengthening the real estate sector and safeguarding the integrity of Nigeria’s financial system”, she said.
In his remarks, the Chairman of REDAN, Lagos state, Mr Tony Kolawole pledged readiness to partner with SCUML in ensuring compliance with AML/CFT/CPF in the real estate sector to uphold financial integrity.
The engagement also provided an opportunity for REDAN members to share practical regulatory and operational challenges affecting the sector, reinforcing the importance of continuous dialogue between regulators and industry stakeholders.

‘Ombugadu Is a Brand, Not a Title’ — PDP Chieftain

China slows oil purchases, showing strategic foresight

200 widows benefit from empowerment outreach in Plateau

-
 Uncategorized6 years ago
FG, states urged to harness flooding for ranching, others with technology – Agbaje
-
 Headlines11 years ago
Breaking: EFCC seals Borno House of Assembly, as Hon members take to their heels
-
 News12 years ago
Nigeria Security Operatives Stage Manhunt For Homosexual Perpetrator
-
 News10 years ago
How 21-year-old Girl fled community over accusation of lesbianism
-
 News11 years ago
Yobe Gov Moves Against Deputy
-
 Opinion7 years ago
7 signs she has friend zoned you
-
Technology5 years ago
Online job placement company headhunts women
-
 Headlines10 years ago
Borno Dep Gov Abducts Another Church Leader